
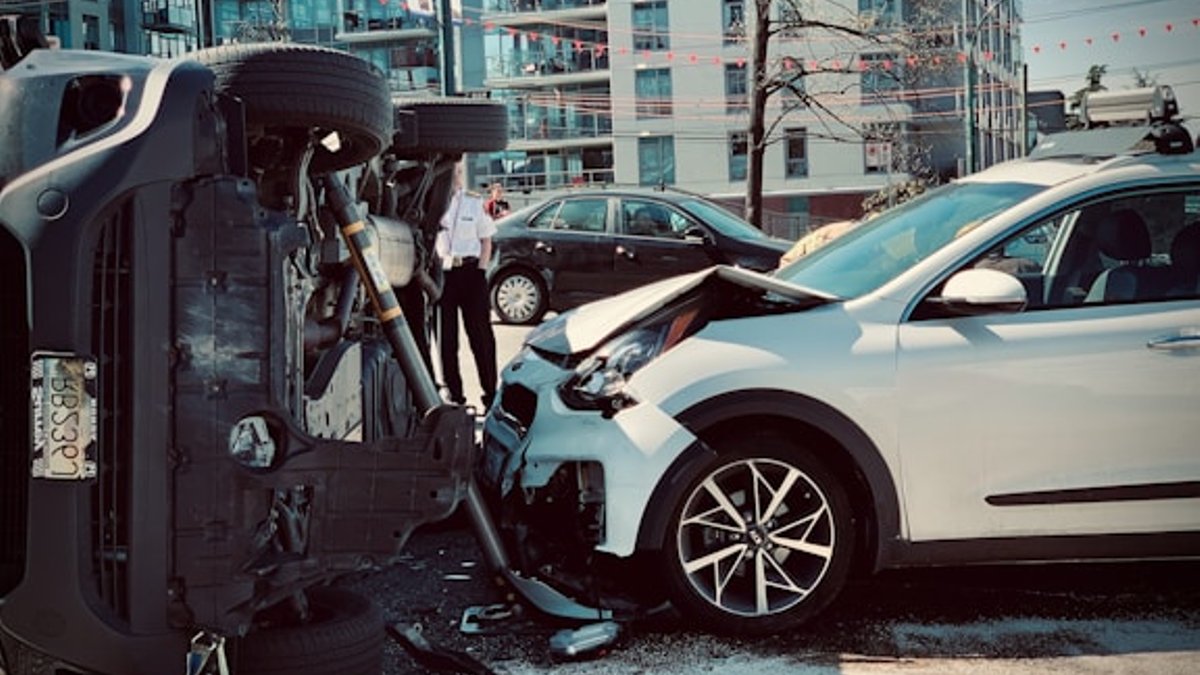
New York’s no-fault insurance system requires your own auto policy to cover medical bills and lost wages after a crash, regardless of fault. The protection includes strict rules and deadlines that can limit further compensation if not followed carefully.
The no-fault system’s limits and coverage details
Personal Injury Protection (PIP), the state’s no-fault coverage, provides up to $50,000 per person for medical treatment. It also covers 80% of lost wages, capped at $2,000 a month, and some household expenses if injuries prevent normal activity. Claims must be filed within 30 days, or insurers may deny them. Insurers often examine treatment delays, using gaps in care to question injury severity.
PIP excludes pain and suffering and does not cover full economic losses for severe injuries. Property damage is handled separately through collision coverage or a claim against the at-fault driver’s liability policy.
Suing the other driver and the “serious injury” standard
New York law permits lawsuits against at-fault drivers only if injuries meet the “serious injury” threshold. The criteria include permanent loss of a body function, a 90-day disability within the first 180 days after the crash, or a medically confirmed limitation affecting daily life. Whiplash and similar soft-tissue injuries may qualify, but insurers frequently contest them unless medical records are detailed and consistent.
Meeting the threshold allows lawsuits for pain and suffering, full lost wages, and damages beyond PIP limits. The burden of proof remains high, and insurers exploit weak documentation. Missing records or delayed medical visits can weaken a claim.
Many drivers are unaware that no-fault coverage does not shield them from liability if their actions caused serious harm. If you were at fault, the other driver’s PIP covers their initial expenses, but they may still sue if their injuries meet the state’s serious-injury threshold. The same rules apply to you—compensation depends on injury severity, not just fault.
Related: Sunway Medical supports national health screening drive
Steps to take at the scene and their importance
Your rights begin immediately after an accident. Police reports serve as critical evidence, providing an independent account of events. Drivers must exchange information—names, license numbers, and insurance details—but nothing beyond that.
Do not apologize or guess about fault. Casual remarks can be used against you later. You are not required to give a recorded statement to the other driver’s insurer, and doing so prematurely is a frequent error. Witnesses leave quickly, so collect their contact information before they disperse. Photograph the scene, vehicles, and injuries—details fade, and insurers use evidence to challenge claims.
Deadlines that determine case outcomes
New York’s filing deadlines are strict. Missing one can forfeit compensation entirely. Key deadlines include:
- 30 days: File a PIP claim with your insurer.
- 30 days: Notify your insurer of an uninsured motorist claim if the at-fault driver lacked coverage.
Early settlement offers from insurers often undervalue injuries. Accepting one without legal advice may mean forfeiting rightful compensation.
The system aims to provide quick financial relief for injured drivers but does not eliminate the right to hold negligent drivers responsible. New York’s rules reward those who document thoroughly, report promptly, and meet deadlines. The difference between a fair settlement and a denied claim often hinges on actions taken in the first few days after a crash.
A lawsuit over graduate student visa time limits highlights how strict deadlines shape legal outcomes in other areas as well.